Consumer Watch: With cable bill, convenience at a price
Ever aspire to be a bill collector? Probably not - neither do I. On my list of unappealing jobs, it ranks somewhere between prison guard and East European Internet scammer.
Ever aspire to be a bill collector? Probably not - neither do I. On my list of unappealing jobs, it ranks somewhere between prison guard and East European Internet scammer.
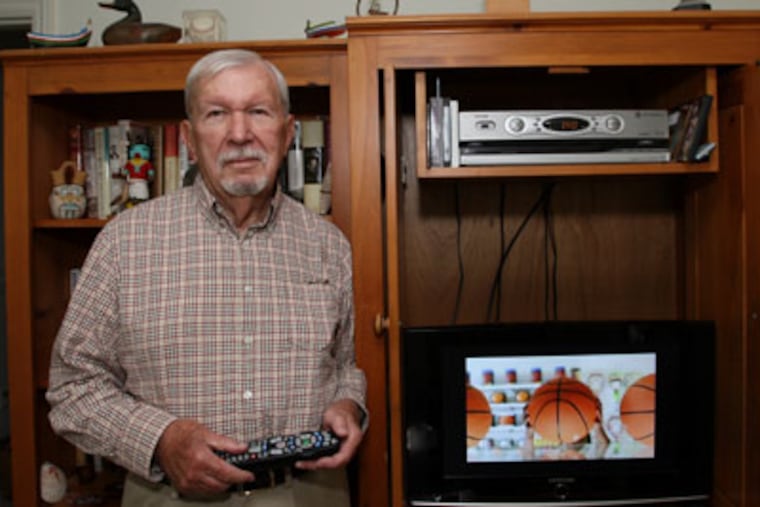
Bob McMackin didn't want to be a collector either. But thanks to a little-noticed aspect of today's high-tech bill-payment system, that's pretty much what he became for a few months earlier this year, when he was forced to dun Comcast for a refund the company agreed he was owed.
McMackin of Downingtown shared his story recently. I'm not quite sure what the moral is - maybe you can help. Perhaps it's simply that convenience can come with a price.
The saga began in the spring in Ocean City, where McMackin and his wife owned a duplex. This year, they decided they had to cut back on travel, so they sold both halves to two of their daughters.
That meant a lot of bills to cancel: water, electricity, gas, phone, cable TV. But McMackin thought he'd taken care of them all, until he looked over the April statement for his Shore bank account and realized something was amiss:
In early April, Comcast Corp. had deducted more than $400 - everything that was left in the bank account, which he also planned to close, and about what he'd have owed for a year's worth of cable TV.
McMackin hadn't expected to see any debit at all because he had called Comcast as soon as he got his bill and hadn't noticed that the bill had arrived after Comcast planned to debit his payment.
Still, he wasn't inclined to quibble over a few weeks of cable. He called again to say he was moving, and says he was promised a refund for the remainder of the year.
And then he called again, and again, and wrote letters. For the next five months, he says, he could barely get anyone at Comcast to listen, let alone pay him his due.
In other words, just what a hapless bill collector has to go through.
Letters to the top
There are some unanswered questions in this story, and one is this: McMackin did get a check from Comcast a few weeks into his dispute. But it was for just $121, he says, and included no explanation. "I don't know where they came up with that figure," McMackin says.
Another is why Comcast didn't bill him for a year's worth of service until two weeks after the company planned to debit his account.
Then there's the question of which of his complaints finally got Comcast's attention.
McMackin says he called six or eight times and, each time, was assured that the problem would be solved. He even wrote two letters to Comcast executive vice president David L. Cohen, whom McMackin recalled from Cohen's days as chief of staff to Philadelphia Mayor Ed Rendell, now Pennsylvania's governor.
"I said, 'You have a reputation as a mover-and-shaker. Move and shake your people to get me my money back,' " recalls McMackin, a retired title-company executive.
Something eventually worked, if not before McMackin's frustration had reached a peak. Last week, Comcast sent McMackin a check for $282. Jeff Alexander, a Comcast spokesman, told me the company had also apologized to McMackin.
"On our side, there was a billing mistake, and we did not refund to the customer in a timely matter," Alexander says, adding that company officials are still trying to pin down what went wrong. "We'll certainly use this as a learning experience."
A better alternative?
It goes without saying that companies, just like people, sometimes make mistakes. Perhaps that's all that went wrong here - that, plus the delayed billing when a timely statement might have averted the entire dispute.
But McMackin also discovered one of the infrequent-but-maddening flaws in direct-debit billing: that if something goes wrong, the consumer is stuck playing bill collector.
Federal laws and regulation provide some basic protections with these electronic funds transfers, though it's unclear how they apply to Comcast's annual billing.
According to the Federal Reserve, for instance, if a company intends to debit a varying amount each month, the consumer is entitled to a written notice at least 10 days before the debit takes place.
Consumers are also entitled to block preauthorized payments by notifying their bank, orally or in writing, at least three business days before a payment is scheduled.
And if a creditor takes more than authorized? Federal rules give the consumer up to 60 days to dispute an unauthorized payment - one more reason it's crucial to carefully review your monthly bank statements.
Is there a better alternative? There may be, if you're a convenience credit card user and never carry a balance.
Comcast, like many other businesses, also allows customers to authorize automatic payments on a credit card - a payment system that affords similar, and often better, dispute rights.
If you make your payments that way, there's no guarantee that a company won't charge you too much, or charge you for a service you believe you've already canceled.
But at least it won't be able to clear out your bank account, and leave you trying for five months to collect what's rightfully yours.